EXIT
Your life’s work.
Your next chapter.
A considered approach to what comes next.

ABOUT GRAYSTONE
A mergers and acquisitions advisory firm focused on helping owners and buyers make consequential decisions with clarity.
About Graystone
Graystone is a Lower Middle Market M&A advisory firm focused on transactions valued from $10 million to $250 million. We help business owners explore exit options, prepare for a sale, and navigate the process through closing. Our sector expertise and coordinated deal teams bring buyer intelligence and personal attention to the decisions that shape your next chapter.
Leadership
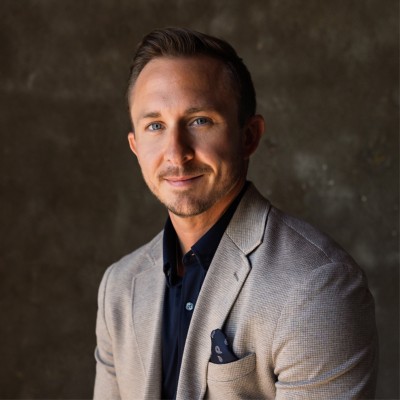
Graystone is led by Chief Executive Officer Nathan Teinert. His letter sets out how the firm approaches every engagement.
Read Nathan’s perspective on the market Graystone serves, how the firm runs a process, and where it is going next.
Office of the CEO
To our clients, our partners, and our colleagues across the advisory community:
Graystone was built on a simple conviction: the owners of America’s best private companies deserve the same caliber of advice that institutional sellers take for granted. For most founders and families, the sale of their business is the single largest financial event of their lives. It happens once, under time pressure, across the table from buyers who transact for a living. The quality of the advisor on their side of that table is not a detail. It is often the difference between a good outcome and the right one.
As we enter the next phase of our growth, I want to share how we see our market, what we have built, and where we are taking the firm.
The lower middle market, businesses with enterprise values between $10 million and $250 million, is the most structurally inefficient segment of American M&A. That inefficiency is exactly why it rewards disciplined advice.
Three forces define it today. First, a generational transfer of ownership is under way. A large cohort of founder-owned companies is approaching succession, and many owners have no internal successor and no prior transaction experience. Second, the buyer universe has never been deeper or more varied. Strategic acquirers, private equity platforms pursuing add-ons, independent sponsors, family offices, and search funds all compete for quality assets, each with a different cost of capital, return hurdle, and view of risk. Third, and most important, pricing dispersion is wide. Two buyers can look at the same business and arrive at valuations that differ by several turns of EBITDA, depending on synergies, integration thesis, and financing structure.
Where dispersion is wide, process is everything. A negotiated sale with one or two familiar buyers captures the low end of that range. A well-run, competitive process captures the high end, and just as importantly, secures terms that protect the seller after closing.
Over the past year Graystone has grown from a focused advisory practice into a national investment bank organized around industry depth. We did this deliberately. We studied how the leading lower middle market banks structure their coverage, then rebuilt that model for the realities of companies one tier below.
Today the firm is organized into national industry teams, each led by a Managing Director and staffed with senior bankers who cover specific subsectors: Consumer; Diversified Industrials & Services; Energy; Health & Life Sciences; Technology; and Professional Services, our newest vertical, now being built.
Sector specialization matters more in the lower middle market than anywhere else. A banker who knows the buyer landscape in a subsector knows which strategics are acquisitive, which sponsors hold adjacent platforms, and which financial metrics that sector’s buyers actually underwrite. That knowledge shortens processes, sharpens positioning, and widens the buyer set well beyond the names an owner would think to call.
We pair that sector depth with a firm-level origination engine and a growing network of trusted advisors, including CPAs, M&A attorneys, wealth managers, and commercial lenders, who refer clients to us because we make them look good in front of the people they serve.
Our methods are our own, but our principles are not a secret. Four of them guide every engagement.
1. Diligence the business before buyers do. Value is won or lost in the quality of earnings. We work with owners early to normalize EBITDA, substantiate add-backs, and frame a defensible net working capital position. Surprises found by a buyer late in diligence become retrades. Issues addressed by the seller up front become part of the story.
2. Position the company for the buyer who will pay the most. Every business has more than one equity story. The narrative that resonates with a strategic, focused on synergies and market access, differs from the one that resonates with a sponsor, focused on durable cash flow and a credible path to a second exit. We build the case for each.
3. Create real competitive tension. We run disciplined, staged processes designed to bring qualified buyers to the table on a common timeline. Competition sets price, but it also improves terms: cash at close versus deferred consideration, earnout mechanics, rollover equity, indemnification caps, and the scope of representations and warranties.
4. Negotiate the whole deal, not the headline. A high purchase price can be eroded through working capital adjustments, escrows, and post-closing obligations. We measure success by what the owner keeps and the risk they carry after closing, not only by the multiple.
This is institutional discipline applied to founder-owned businesses. It is what our clients expect, and it is what sophisticated buyers respect.
Our direction for the years ahead rests on three commitments.
Depth before breadth. We will keep adding senior bankers only where they deepen our sector expertise. Growth that dilutes specialization is not growth we want.
A complete view of the transaction. Owners increasingly ask for help on both sides of the table, whether they are selling, acquiring to build scale, or planning a transition years out. We are building our buy-side advisory practice and strengthening relationships across the transaction ecosystem so our clients get coordinated advice at every stage.
Proprietary infrastructure. We are investing in technology and data that let our bankers identify buyers, track market activity, and manage processes with greater precision. The lower middle market has long run on relationships and spreadsheets. We believe the firms that win the next decade will pair strong relationships with better information.
To our peers in the advisory community: we see the lower middle market as large enough to reward many good firms, and we welcome collaboration where it serves the client.
To the business owners reading this: you spent decades building something of lasting value. The transition of that business deserves the same care, rigor, and ambition you brought to building it. That is the standard we hold ourselves to on every engagement, and it is why we are building Graystone the way we are.
Thank you to our clients for their trust, to our referral partners for their confidence, and to our team for the work behind every result.
With appreciation,
Nathan TeinertCEO, Graystone
What we believe
Complex decisions deserve plain language and honest answers.
Confidentiality protects owners, employees, and value.
A broad buyer network creates real options.
Success-based fees tie our outcome to yours.
Who we serve
Graystone Direct
Tell us where you are and what you are weighing. We will listen first.